

Key considerations for correctly managing Christmas hampers in payroll
Every December, many companies give their employees a Christmas hamper. Although it is considered a gift, for employment and tax purposes it constitutes remuneration in kind. Therefore, it must be reflected in payroll, be subject to personal income tax (IRPF) and, as a general rule, be included in Social Security contributions.
How is the Christmas hamper included in payroll?
The company must record the hamper as remuneration in kind and apply the corresponding tax and Social Security contribution treatment. To do this correctly:
- The hamper is valued at its cost, including VAT.
- It is added to the December payroll as remuneration in kind. The employee does not receive this amount in cash, but it counts towards IRPF and Social Security contributions.
- The IRPF payment on account is calculated by applying each employee's withholding tax rate to the value of the hamper. This is equivalent to the withholding applied to salary, but for remuneration in kind. The company pays this amount to the Spanish Tax Agency using Form 111 and includes it in the annual summary, Form 190.
- Social Security contributions are calculated on the value of the hamper, just as they are on the rest of the salary.
How much money does an employee lose from their payroll?
Let's imagine a Christmas hamper worth €80 given to an employee with an IRPF withholding tax rate of 15%. The company can choose to pass the payment on account on to the employee or cover it itself.
This is how each scenario would work:
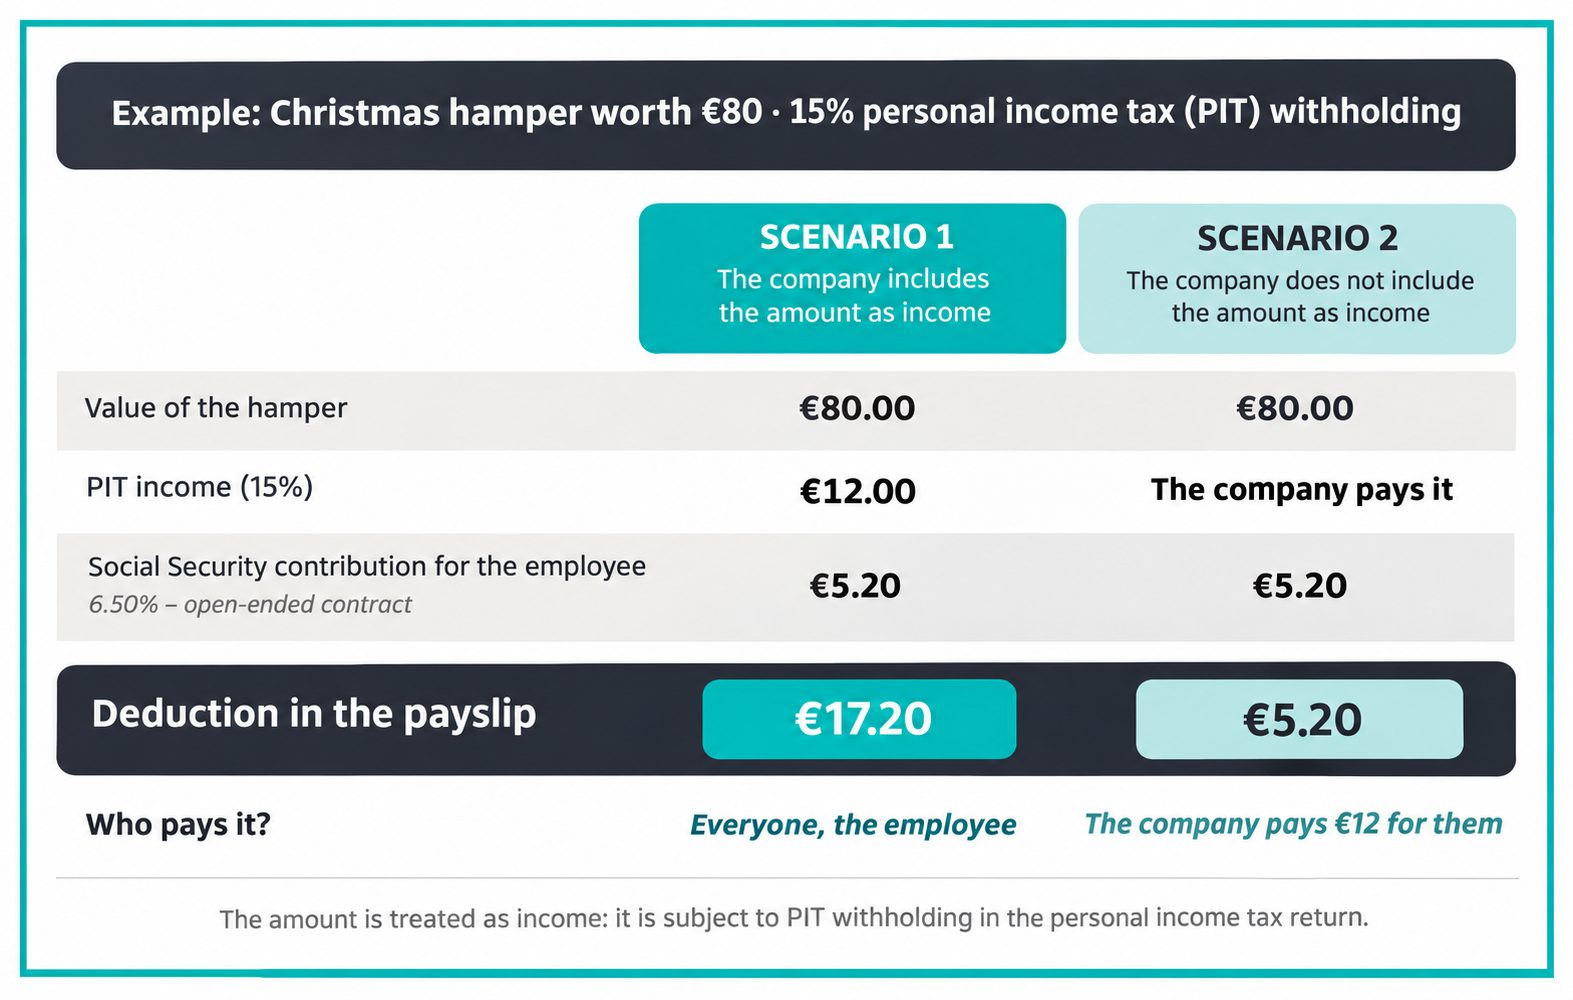
Scenario 1: The company passes the payment on account on to the employee
- The employee sees a deduction of €17.20 from their payroll: €12 in IRPF and €5.20 in Social Security contributions (6.50% for a permanent employment contract).
- The €12 in IRPF is not an additional expense. It works in the same way as the withholding applied to their salary each month: when filing their income tax return, it counts as tax already paid.
Scenario 2: The company covers the payment on account
- The employee only sees a deduction of €5.20 from their payroll for Social Security contributions (6.50% for a permanent employment contract).
- The company pays the €12 in IRPF on the employee's behalf.
- Since the company is also giving the employee those €12, the Spanish Tax Agency adds this amount to the value of the hamper: it is as if the employee had received €92 (€80 for the hamper + €12).
How to calculate it using your own figures
To adapt the example to any Christmas hamper and any employee, only two calculations are needed:
- IRPF payment on account = value of the hamper × employee's withholding tax rate.
- Employee's Social Security contribution = value of the hamper × 6.50% for permanent contracts or 6.55% for temporary contracts (2026).
The employee's Social Security contribution rates for 2026 are broken down as follows:
- Common contingencies: 4.70%.
- Unemployment: 1.55% (1.60% for temporary contracts).
- Vocational training: 0.10%.
- Intergenerational Equity Mechanism (MEI): 0.15%.
What happens if an employee refuses the hamper?
If the employee voluntarily declines the hamper and receives neither the hamper nor any alternative compensation, there is no remuneration in kind to include in payroll.
It is advisable to keep a written record of the refusal to avoid potential misunderstandings.
Can the company stop providing Christmas hampers?
The answer depends on how the hampers have been provided up to now. There are two possible scenarios:
- If the hamper has been provided on a one-off or occasional basis: the company may decide not to provide it, as no entitlement has been established for employees.
- If the hamper has been provided regularly for years: it may have become an acquired right (a more favourable employment condition) for employees, even if it has not been documented in writing. In this case, the company cannot simply withdraw it. Instead, it must justify the reason (for example, economic or organisational grounds), inform employees in advance and, if it affects a significant number of people, negotiate beforehand with the employees' legal representatives.
What are the most common mistakes?
The most common mistakes are providing the hamper without including it in payroll or including it for IRPF purposes but forgetting to pay Social Security contributions on it. Both errors may result in adjustments by the Spanish Tax Agency or Social Security authorities, together with the corresponding surcharges and interest.
Conclusion:
The Christmas hamper is much more than a gesture of appreciation: it is remuneration in kind and must be treated as such.
Managing it correctly helps prevent payroll errors and potential adjustments by the Spanish Tax Agency or Social Security authorities.
Related content


